How to Register a Homemade Trailer in Massachusetts: The Ins, Outs & What You Need to Know


Built your own trailer in Massachusetts? Before you hook it up and hit the road, you need to get it properly registered.

Homemade trailers are a little different from buying a new trailer from a dealer. There may be no manufacturer’s certificate of origin, no traditional VIN, and—depending on the trailer’s weight—no title.

The good news? You can register a homemade trailer in Massachusetts.

The process just depends on how the trailer is built and, most importantly, its gross vehicle weight rating (GVWR).

Here’s what Massachusetts trailer owners need to know.

First: How much does the trailer weigh?

This is the most important question.

Massachusetts generally divides trailers into two categories:

Homemade trailer weighing 3,000 pounds or less

If your homemade trailer has a GVWR of 3,000 pounds or less, it does not require a Massachusetts certificate of title.

Instead, it can generally be registered as a trailer without going through the title process. Massachusetts RMV materials specifically provide for registration of homemade trailers without a conventional VIN, using a pseudo-VIN assigned by the RMV system.

Homemade trailer over 3,000 pounds

This is where things get more complicated.

A homemade trailer with a GVWR over 3,000 pounds must be titled, and Massachusetts requires the trailer to obtain a Massachusetts-assigned VIN.

The RMV specifically lists homemade trailers over 3,000 pounds among the vehicles eligible for a Massachusetts-assigned VIN.

The State Police inspect the trailer as part of the VIN assignment process. The assigned VIN begins with “MA” followed by five digits and is affixed to the trailer.

What paperwork do you need for a homemade trailer?

Here’s the part that catches many do-it-yourself trailer builders by surprise.

If you built the trailer yourself, you don’t have a traditional dealer invoice showing what you paid for it.

Massachusetts RMV guidance says the owner should provide a detailed, handwritten statement of the costs incurred in constructing the trailer.

That statement should include the materials and costs that went into building it. Receipts for materials can also be submitted as supporting documentation.

The statement must be:

  • Detailed
  • Signed
  • Dated
  • Dated as of when the trailer was completed and road-ready

It does not have to be notarized. The completion date is also used to determine the trailer’s model year.

Why does the RMV want to know what you spent?

Because Massachusetts uses the value of the materials and construction costs to determine the applicable sales tax.

In other words, don’t assume that because you built it yourself, there is no sales tax issue.

Keep those receipts!

What about the VIN?

This depends on the trailer.

Trailer 3,000 pounds or less

A homemade trailer under the title threshold may not have a traditional VIN. Massachusetts has a process for these trailers to be registered using an RMV-generated pseudo-VIN. The RMV’s EVR guidance specifically identifies homemade trailers without VINs and provides for the system to create a pseudo-VIN for registration purposes.

Trailer over 3,000 pounds

You’ll need a Massachusetts-assigned VIN.

The process involves submitting the appropriate VIN application and supporting documentation to the RMV and having the trailer inspected by the Massachusetts State Police.

Don’t confuse this with simply walking into an inspection station and asking for a VIN. The assigned-VIN process is a separate RMV/State Police procedure.

Do I need a title?

Here’s the simple rule:

3,000 pounds or less: No Massachusetts title is required.

Over 3,000 pounds: Yes. A certificate of title is required.

The current Massachusetts title fee is $75, in addition to applicable taxes and registration fees.

Getting the trailer registered

Once you’ve determined which category your trailer falls into and gathered the necessary documentation, you’ll need a Registration and Title Application (RTA).

A Massachusetts insurance agent can complete the insurance portion of the application and process the registration through the appropriate RMV system or help you determine what needs to be submitted to the RMV. Massachusetts specifically encourages customers to use participating insurance agents and other RMV business partners for registration transactions.

For a homemade trailer over 3,000 pounds, however, make sure the VIN/title requirements have been satisfied before expecting a routine registration transaction to go through.

Don’t forget the trailer’s equipment

Registering a homemade trailer isn’t the same thing as saying the trailer is automatically legal or safe to operate.

Massachusetts law allows the Registrar to refuse or suspend registration if a motor vehicle or trailer is unsafe, improperly equipped, or otherwise unfit to operate.

Before putting your homemade trailer on the road, make sure it is properly equipped and roadworthy, including the appropriate:

  • Lights
  • Brake and electrical components
  • Tires and wheels
  • Safety chains
  • Hitch/coupler
  • Reflectors
  • Fenders or other required equipment
  • Load securement

The exact requirements can depend on the type, size, weight and use of the trailer.

Does a homemade trailer need an inspection?

This is another area where how you use the trailer matters.

Massachusetts has an annual safety inspection program covering motor vehicles, trailers, semi-trailers and converter dollies.

The RMV also specifically notes that trailers used commercially, regardless of registered weight, must pass an annual safety inspection.

So don’t assume that because your trailer is homemade—or because it’s a small personal-use trailer—it is automatically exempt from every inspection requirement.

If the trailer will be used commercially, this becomes particularly important.

What about insurance?

This is where you should talk to your insurance agent before you build the trailer, not after you’ve registered it.

Trailer coverage can depend on:

  • Whether the trailer is personally or commercially used
  • What the trailer is designed to carry
  • Its value
  • Its weight
  • Whether it is used with a personal or commercial vehicle
  • Whether it is a utility, boat, cargo, or specialty trailer

Some personal auto policies provide certain coverage for trailers, but don’t assume your homemade trailer is automatically covered for everything simply because your automobile is insured.

For example, liability coverage and physical-damage coverage are two different questions.

If you’ve put several thousand dollars into building a custom trailer, you should specifically ask your insurance agent how the trailer itself is covered.

A common mistake: “I built it, so I don’t need paperwork.”

Unfortunately, that’s not how Massachusetts works.

Even though you built the trailer yourself, once you intend to operate it on Massachusetts public roads, you still have to satisfy the Commonwealth’s registration requirements.

And if the trailer is over 3,000 pounds, the VIN and title requirements become substantially more involved.

Homemade Trailer Registration Checklist

Before heading to the RMV, make sure you’ve worked through this list:

☐ Determine the trailer’s GVWR

☐ Determine whether the trailer is over or under 3,000 pounds

☐ Gather receipts for materials and components

☐ Prepare a detailed statement of construction costs

☐ Determine whether a Massachusetts-assigned VIN is required

☐ Complete the appropriate RTA paperwork

☐ Obtain the appropriate insurance

☐ Complete the title process if the trailer is over 3,000 pounds

☐ Pay applicable sales tax, title and registration fees

☐ Make sure the trailer meets Massachusetts equipment and safety requirements

☐ Determine whether annual inspection requirements apply

The Bottom Line

Building your own trailer can save money and let you create exactly what you need—but Massachusetts doesn’t treat a homemade trailer exactly like a factory-built trailer.

The 3,000-pound threshold is the big dividing line:

3,000 pounds or less: generally no title, and a homemade trailer can be registered through the RMV’s registration process.

Over 3,000 pounds: title required, Massachusetts-assigned VIN required, and State Police inspection is part of the VIN process.

And regardless of weight, don’t overlook the insurance side.

At Johnson & Rohan Insurance, we’re happy to help Massachusetts trailer owners figure out the insurance and registration requirements before they get stuck at the RMV.

This article is intended as general information and is not legal advice. Massachusetts RMV requirements can change. For unusual, custom-built or commercial trailers, we recommend confirming the current requirements with the Massachusetts RMV before beginning the registration process.
Happy Labor Day Weekend


Happy Labor Day!

Wishing everyone a safe and relaxing holiday weekend!

Our office will be closed Monday, September 7th, in observance of Labor Day. We’ll reopen with our regular office hours on Tuesday, September 8th.

Thank you, and enjoy the holiday weekend!

Of course claims don’t always happen during office hours.

If you have an auto or home claim, with most companies, you can report the claim 24 hours a day/ 7 days per week.

Have your policy number ready and dial or click:

Travelers: 1-800-252-4633
Safety Insurance: 800-951-2100
Vermont Mutual: 1-800-435-0397

Plymouth Rock: 1-844-346-1225

Mass Property: 1-800-392-6108
Progressive Insurance: 1-800-274-4499
Bristol-West: 1-800-272-7865

Swyfft Insurance: 1-877-799-3389
Hagerty Insurance: 1-877-922-9701
Utica First Insurance: 1-800-456-2139

MAPFRE/Commerce: 1-866-351-2548
Grundy Insurance: 866-338-4006

Openly Insurance: 888-808-4842

Embark General: 800-809-5747

Stay safe and don’t hesitate to reach out to us during normal office hours.

Happy Independence Day from Johnson & Rohan Insurance


As we celebrate Independence Day, all of us at Johnson & Rohan Insurance would like to wish you and your family a safe, relaxing, and happy Fourth of July.

Please note that our office will be closed on Friday, July 3, in observance of the Independence Day holiday. We will reopen on Monday, July 6, ready to assist with all of your insurance needs.

The Fourth of July has always been one of our favorite holidays. It’s a time for backyard cookouts, time at the beach or lake, neighborhood parades, fireworks, and, most importantly, spending time with family and friends.

It’s also a chance to pause and appreciate something even greater—the freedoms we enjoy and the opportunity to live, work, and raise our families in this remarkable country. While no nation is perfect, we are incredibly fortunate to call the United States home and to enjoy the liberties and opportunities that so many have sacrificed to protect.

Here in Massachusetts, we’re especially grateful for the communities we serve. For over three decades, you’ve trusted Johnson & Rohan Insurance to help protect your homes, automobiles, businesses, and families. That trust means more to us than you know, and we sincerely thank you for allowing us to be part of your lives.

Whether you’re traveling, hosting friends, enjoying a barbecue, or watching fireworks with loved ones, we hope your holiday is filled with great memories—and that everyone stays safe along the way.

From our family to yours, thank you for your continued confidence in Johnson & Rohan Insurance.

Happy Independence Day, and Happy Fourth of July! God Bless America.

Is the Massachusetts Insurance Market Finally Calming Down?

Massachusetts Insurance

If you’ve opened your Massachusetts insurance renewal over the past few years and thought, “Seriously? Another increase?” you’re not alone.

The insurance market has been a bit of a roller coaster lately. Rising repair costs, inflation, severe weather, and more expensive claims have pushed premiums higher across both home and auto insurance.

The good news? We’re starting to see a few encouraging signs.

While rates haven’t exactly started falling, insurance companies seem to be loosening up a bit. Some carriers are becoming more competitive, underwriting guidelines are easing in certain situations, and coverage options that were difficult to obtain a year or two ago are becoming more available.

In plain English: insurance companies are saying “yes” more often than they were.

We’re also seeing more options for higher-value homes, larger liability limits, and certain risks that had become difficult to place during the toughest part of the market cycle.

That doesn’t mean every customer will see lower premiums. Claim costs remain high, and many policies are still experiencing rate increases. But the marketplace feels more stable today than it did a few years ago.

For consumers, that’s a positive development.

As carriers become more competitive, it becomes increasingly important to review your insurance periodically. The company that offered the best value three years ago may not be the best fit today.

At Johnson & Rohan Insurance, we keep an eye on the market so you don’t have to. If it’s been a while since you’ve reviewed your coverage, now might be a good time to take another look.

The Massachusetts insurance market isn’t exactly “soft” yet—but for the first time in a while, it’s showing signs of becoming a little friendlier.

The Future of Insurance in Massachusetts: 2040

If you’ve noticed your insurance costs rising in recent years, you’re not alone.

Homeowners and drivers across Massachusetts are asking a simple question:

Are insurance prices going to keep going up—or is this temporary?

The short answer: insurance is entering a long-term shift driven by technology, construction costs, climate risk, and vehicle complexity.

Here’s what that means for the next 10–20 years.


Will Insurance Costs Go Up or Down?

In Massachusetts and across the U.S., most long-term projections point in one direction:

Insurance costs are expected to continue rising over the next 10–20 years.

This is not just a pricing trend—it’s driven by real-world cost increases, including:

  • Higher home rebuilding and repair costs
  • Increasingly advanced vehicle technology
  • More expensive medical and liability claims
  • Severe weather and climate-related losses
  • Labor shortages in construction and repair industries

When it costs more to repair or replace something, insurance must reflect that reality.


The Future of Auto Insurance: Safer Cars, Higher Repair Costs

Cars are becoming safer and more advanced, with features like:

  • Lane assist and collision avoidance systems
  • Electric vehicle (EV) platforms
  • Advanced onboard computers and sensors
  • Partial and full autonomous driving capabilities

While these features may reduce accidents, they significantly increase repair costs.

A simple bumper repair today may involve recalibrating multiple sensors and onboard systems.

Expected impact:

  • Fewer accidents overall
  • Higher cost per claim
  • More specialized repair networks
  • Continued upward pressure on premiums

Auto insurance will not disappear—it will evolve with vehicle technology.


Home Insurance in Massachusetts: Stronger Homes, Higher Replacement Costs

Homes are improving in durability and technology, including:

  • Fire-resistant building materials
  • Smart home monitoring systems
  • Leak detection and prevention technology
  • Energy-efficient construction standards

However, the most important factor in insurance pricing is still:

Rebuilding cost

In Massachusetts, construction and labor costs have risen significantly over the past decade, and that trend is expected to continue.

Expected impact:

  • More expensive claims when losses occur
  • Continued pressure on home insurance premiums
  • Increased importance of accurate replacement cost coverage

Even as homes become safer, they are also more expensive to rebuild.


Weather and Risk Trends in Massachusetts

While Massachusetts is not the highest-risk catastrophe state, insurers are increasingly factoring in:

  • Nor’easters and winter storm damage
  • Coastal exposure and storm surge risk
  • Freeze-thaw structural damage cycles
  • Increasing variability in seasonal weather patterns

Insurance pricing is influenced not just locally—but nationally.

Large-scale losses in other regions can impact pricing across the entire country.


How Technology Will Change Insurance

The biggest transformation may not be what we insure—but how insurance works.

Over the next two decades, we expect:

  • Faster claims processing powered by AI
  • More personalized pricing based on real-time data
  • Smart homes and vehicles communicating risk data
  • Fully digital policy management systems

Insurance will become more responsive, more automated, and more data-driven.

But human guidance will still matter—especially when decisions are complex or high-value.


What This Means for Massachusetts Consumers

Insurance is shifting from a simple purchase to an ongoing risk management strategy.

Consumers should expect:

  • More frequent policy reviews
  • Greater differences in coverage quality between carriers
  • Increased importance of proper coverage limits
  • Less focus on price alone—and more on protection

The goal is no longer just finding the cheapest policy.

It’s ensuring you are properly protected in a changing world.


Final Thoughts

Even as technology improves and homes and cars become more advanced, one truth remains:

Risk does not disappear—it evolves.

Insurance will continue to change alongside the world around it.

Our role as an independent agency is to help clients stay ahead of those changes—not react after the fact.

Because in the future, the most important question won’t be:

“How much does it cost?”

It will be:

“Am I properly protected for what comes next?”

Trusted Home & Auto Insurance in Lynnfield, MA

Lynnfield. MA

For over 30 years, Johnson & Rohan Insurance has proudly served the families and businesses of Lynnfield, Massachusetts. As a local, independent insurance agency, we understand the community—from MarketStreet Lynnfield to Town Hall, seasonal events, and neighborhood favorites. This local knowledge helps us provide personalized home insurance in Lynnfield and auto insurance near Lynnfield MA that fits your life and budget.

We represent over 30 top-rated insurance carriers, shopping across multiple companies to find the best coverage at the most competitive rates. Whether you need homeowner, condo, apartment, auto, or umbrella insurance, we focus on protecting what matters most to you.

At Johnson & Rohan, we treat our clients like family. From answering questions to guiding you through a claim, we make insurance simple and stress-free. That’s why so many Lynnfield residents trust us—and refer their neighbors—to keep their homes and vehicles protected.

If you’re looking for local insurance expertise in Lynnfield, MA, contact us today. We’re ready to provide coverage that fits your life, your home, and your budget.

Spring? Hopefully …

Spring has a way of sneaking up on us in Massachusetts. One day you’re stepping over snowbanks, the next you’re hearing birds again and noticing the sun sticking around a little longer each evening. This year, the first official day of spring—the vernal equinox—arrives on March 20. It’s a welcome milestone, but as any New Englander knows, it doesn’t mean winter is finished with us just yet.

March and April can be unpredictable. Warm afternoons can quickly give way to freezing nights, late snowstorms, heavy rain, and those classic freeze-thaw cycles that seem determined to test every part of your home. It’s a season of transition—and a good time to make sure your property is ready for whatever comes next.

A few simple steps now can help prevent headaches later:

Keep an eye on your roof and gutters.
Snow and ice may be melting, but that runoff has to go somewhere. Make sure gutters and downspouts are clear so water can flow away from your home. Ice dams and clogged gutters can lead to leaks just when you think you’re in the clear.

Watch for water around your foundation.
Melting snow combined with spring rains can saturate the ground quickly. Check that water is draining away from your foundation, and consider testing your sump pump if you have one. A small issue now can turn into a flooded basement fast.

Inspect for winter wear and tear.
Take a walk around your property. Look for cracked walkways, loose shingles, damaged siding, or anything that may have taken a beating over the winter months. Catching these early can prevent more costly repairs down the road.

Be cautious with early outdoor projects.
It’s tempting to jump into yard work or fire up equipment at the first sign of warmth. Just remember that the ground may still be soft, and temperatures can dip below freezing again. Proceed carefully to avoid damage to landscaping—or injuries.

Review your coverage.
Seasonal transitions are a good time to revisit your insurance policies. Whether it’s making sure your home is properly covered for water damage or confirming limits and deductibles still make sense, a quick review can bring peace of mind heading into the months ahead.

Spring in Massachusetts is a mixed bag—but that’s part of its charm. The days get brighter, the air feels lighter, and there’s a sense of renewal that’s hard to miss. Just don’t pack away the winter gear too quickly. Around here, we know better.

If you have questions about your home coverage or want to make sure you’re prepared for whatever this spring brings, we’re always here to help.

No Vacancy

Heads Up: Vacant Homes and Insurance – Why We Need to Know

Hey, it happens — tenants move out, you’re between renters, a home is being renovated, or maybe it’s just sitting on the market waiting for the right buyer. Life happens.

But here’s something a lot of people don’t realize: once a property sits empty for too long, your insurance coverage can change — sometimes drastically.

And if we don’t know the property is vacant, a claim could be denied. That’s a scary thought, but it’s avoidable.


Unoccupied vs. Vacant — There’s a Difference

Insurance companies care about the details:

  • Unoccupied: The home is furnished and utilities are on, but no one is living there.

  • Vacant: The home is mostly empty — furniture gone, utilities may be off, nobody living there.

Most policies have a vacancy rule — usually after 30 or 60 consecutive days, the insurer may limit coverage for theft, fire, water damage, vandalism, or even deny a claim completely.

Basically: an empty house is riskier, and insurers treat it that way.


Real-World Scenario

Imagine this:

A rental tenant moves out in January. You’re planning to rent it again in spring. The place sits empty for 75 days.

Then — boom — a pipe bursts. You file a claim.

If we weren’t told the house was vacant, the insurance company might deny the claim because it was empty too long. That’s not a “maybe” — it’s exactly how vacancy clauses work.


Why You Should Call Us

When a property becomes vacant or unoccupied, give us a call immediately. It takes just a few minutes, and we can:

  • Add a vacancy endorsement

  • Switch to a vacant dwelling policy if needed

  • Adjust coverage to keep you protected

It might cost a little more temporarily, but trust me — it’s way cheaper than an uncovered loss.


Even Short-Term Vacancies Count

Don’t assume a couple months is fine. This includes:

  • Homes between tenants

  • Seasonal or vacation homes

  • Properties being renovated

  • Homes listed for sale

  • Inherited or probate properties

If it’s empty, we need to know.


Bottom Line

We’re here to protect you — but insurance policies are contracts, and vacancy rules are real.

So, if a property is going to be unoccupied or vacant, please call us. A quick phone call now can save you from a big headache later.

Ice Dams Are Back: What Massachusetts Homeowners Need to Know

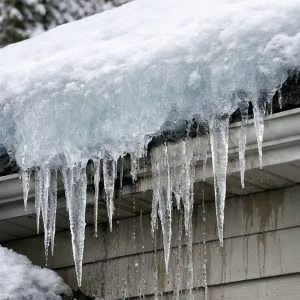
After nearly two feet of snow across Massachusetts, ice dams are making an unwelcome return. For anyone who lived through the winter of 2015, this feels familiar—and not in a good way. As snow piles up on roofs and temperatures swing above and below freezing, water has nowhere to go… except into your house.

And yes—our phones are already ringing.

What Is an Ice Dam?

An ice dam forms when:

  • Heat escapes from your home and melts snow on the roof

  • Melted water runs down toward the colder roof edge

  • The water refreezes at the eaves, forming a dam

  • Additional melting snow backs up behind it

That backed-up water can then:

  • Seep under shingles

  • Enter walls, ceilings, and insulation

  • Cause interior water damage, mold, and ruined finishes

At that point, the damage is already done.

Is Ice Dam Damage Covered by Home Insurance?

The good news:
Most standard Massachusetts homeowners insurance policies do cover damage caused by ice dams—specifically the resulting water damage to the interior of the home.

The not-so-good news:

  • Your policy deductible will apply

  • You’ll likely lose your loss-free discount at renewal

  • Coverage applies to the damage, not fixing the underlying cause

In other words: insurance helps you recover, but it doesn’t prevent the problem.

What Insurance Doesn’t Do

This is a common misconception, so it’s worth being clear.

Insurance companies:

  • ❌ Will not remove snow or ice from your roof

  • ❌ Will not send someone up with a pick axe or heat cables

  • ❌ Will not redesign your roof or insulation

Instead, they expect homeowners to:

  • Take reasonable steps to prevent further damage

  • Hire qualified professionals to address the ice and make repairs

Failure to mitigate can make a bad situation worse—and complicate a claim.

What To Do If You Suspect an Ice Dam

If you’re seeing water stains, dripping, or bulging ceilings:

  1. Call your insurance agent early
    We can help you understand coverage before things escalate.

  2. Document the damage
    Take photos and videos of stains, leaks, and affected areas.

  3. Stop the water if possible
    Safely placing buckets or creating drainage channels can help limit damage.

  4. Hire a professional
    Look for licensed roofers or ice-dam removal specialists. Avoid DIY roof work—it’s dangerous and often ineffective.

  5. Keep receipts
    Emergency mitigation costs are often reimbursable.

Preventing Ice Dams Going Forward

While no home is immune, prevention goes a long way:

  • Improve attic insulation and ventilation

  • Seal air leaks that allow heat to escape

  • Remove heavy snow from roofs after major storms

  • Consider professional evaluation if ice dams are recurring

Many homeowners don’t realize that ice dams are often a building science issue, not a roofing defect.

We’ve Been Here Before—and We’re Here to Help

Ice dams are stressful, messy, and disruptive—but they’re also something we deal with every winter in Massachusetts. If you’re worried, seeing signs of damage, or just want to understand how your policy responds, give us a call.

A quick conversation now can save a lot of frustration later.


Winter Storm Alert

Winter Storm Alert: With a significant snowstorm and extreme cold in the forecast, now is the perfect time to protect our homes and businesses from winter weather damage.


In an attempt to stay ahead of common cold weather risks such as frozen pipes, ice dams and more, we offer:

Freezing Weather Preparation Tips

Consider sharing the following reminders with our customers:

  • Keep thermostat settings consistent – never below 55°F
  • Open cabinet doors to allow warm air to circulate around pipes
  • Let faucets drip slowly during extreme cold
  • Insulate exposed pipes in basements, garages, and crawlspaces
  • Know where the main water shut off valve is located
  • Clear snow and ice from roof edges to help minimize ice dams

Ice Dams

An ice dam is an accumulation of ice at the lower edge of a sloped roof, usually at the gutter. When interior heat melts the snow on the roof, the water will run down and refreeze at the roof’s edge, where temperatures are much cooler. Eventually, the ice builds up and blocks water from draining off of the roof. This, in turn, forces the water under the roof covering and into your attic or down the inside walls of your house. Once an ice dam forms, the potential damage can be serious.

Taking the following steps will decrease the likelihood that ice dams will form or, at least, will reduce their severity.

  • Keep the attic well ventilated. The colder the attic, the less melting and refreezing on the roof.
  • Keep the attic floor well insulated to minimize the amount of heat rising through the attic from within the house.

As an extra precaution against roof leaks in case ice dams do form, install a water repellent membrane under your roof covering.

Unfortunately, ice dams may be unavoidable if your home has recessed lighting near the roof. Heat generated from these lights melts snow which then contributes to ice dam buildup. The only sure way to avoid this problem is to eliminate recessed light fixtures near the roof.

Freezing Pipes

Frozen water in pipes can cause water pressure buildup between the ice blockage and the closed faucet at the end of a pipe which leads to pipes bursting at their weakest point. Pipes in attics, crawl spaces and outside walls are particularly vulnerable to freezing in extremely cold weather. Holes in outside walls for TV, cable or telephone lines allow cold air to enter the house.

To keep water in pipes from freezing, take the following precautions:

  • Fit exposed pipes with insulation sleeves or wrapping to slow the heat transfer. The more insulation the better.
  • Seal cracks and holes in outside walls and foundations near water pipes with caulking
  • Keep cabinet doors open during cold spells to allow warm air to circulate around pipes, particularly in the kitchen and bathroom.
  • Keep a slow trickle of water flowing through faucets connected to pipes that run through an unheated or unprotected space. Drain the water system especially if your house will be unattended during cold periods.
Johnson & Rohan