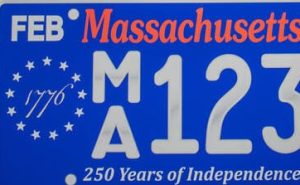
MA 1776 “250” Plates …

The new, MA 1776 “250” plates have generated quite the buzz. We’ve had numerous clients trade in their old plates to get these new, passenger special series (PAS) plates.
The cost is $100 every 2 years (vs. regular, passenger plates which are $60 every 2 years).
Surprisingly, or maybe not, the plates are in such high demand that the RMV tells us they’ve run out of plates and it’s going to take 8 – 10 weeks for them to be issued.
In the meantime, however, the RMV will issue a paper, temporary plate until consumers receive their new plates.
We asked AI if it’s true that the RMV has run out of new 1776 “250” plates:
Yes, due to unexpectedly high demand, the Massachusetts RMV is currently experiencing an 8–10 week delivery delay for the new MA-250 special license plates. The information you received from the RMV is accurate. 
Here is what you need to know about the delay:
  • Official notice: The RMV has issued a training update for dealerships and other partners to inform customers of the delay. An email was also sent to recent customers who ordered the plates.
  • Temporary plates: Customers who do not have existing plates when they order will be issued temporary plates to use while they wait for their permanent ones. If your temporary plates expire before the new ones arrive, you can renew them online.
  • High demand: The plates were made available on May 22, 2025, and the surge in orders has led to a production and delivery backlog. 
Canine Conundrum


At Johnson & Rohan Insurance we have a soft spot for our canine friends. Part of the homeowner insurance application process is the question: Do you own a dog? If the answer is: “yes,” the next question is: What breed is your dog?

One company’s underwriting manual states:

A risk is not eligible if any animal owned or kept has shown dangerous propensities or has been involved in any occurrence that resulted in bodily injury or property damage. A risk is also ineligible if the prospective insured(s) or applicant(s) own or keep any of the following animals: Akitas, American Staffordshire Terrier, Bull Mastiff, Cane Corso, Chow, Dingo, Doberman Pinschers, German Shepherds, Korean Jindo, New Yorkie, Pit Bull Terriers, Presa Canario, Rottweilers, Staffordshire Terrier, St. Francis Terrier, Wolf Hybrids, Mixed Breeds that include any of the above animals, Guard/Attack dogs, and any animal with a past history of biting or that demonstrates aggressive behavior.

According to The Insurance Information Institute, in 2024, U.S. insurers paid out a total of $1.6 billion in dog-related injury claims. The average cost per claim rose by 18% from the previous year to $69,272.

While we understand the insurance industry’s concern about dogs and dog bites, we wish there was a way to review individual dogs and their history of aggressive behavior. For instance, we know the sweetest German Shepherd and the only thing he would ever bite is his food. Likewise, we’ve met very sweet Pit Bull Terriers.

Unfortunately, it seems, until dog bite claims subside, some insurance companies are going to maintain their “do not insure” list of dog breeds.

What can you do if you have a “banned breed?”

Contact us at Johnson & Rohan Insurance. We are an independent insurance agency that writes with multiple companies. We will find a market for your home insurance, no matter what kind of dog Fido is.

Safety Insurance E-Bill

Safety Insurance E-Bill Program


If you are insured with Safety Insurance and have signed up for their EFT billing program, billing charges have been $1 per installment.

A client recently got in touch with us, asking why his automatic installments are now $7?

In order to take advantage of $1 installments, Safety Insurance requires that you sign up for their new “E-Bill” program.

You can go to:  www.SafetyInsurance.com

If you don’t have an account, you will want to set one up. If you already have one, go to your account, click on each of your policies and sign up for “E-Bill.”

This will reduce the billing fee from $7 to $1.

If you have any problems signing up online, Safety Insurance will walk you through the process by calling:  800-951-2100 (extension 2, then 4 to get a live person).

Please call us with any questions.

Collision Coverage – If Hit by a Stolen Vehicle

Collision Coverage - If Hit by a Stolen Vehicle

I read an interesting article in the MassAgent newsletter from the Massachusetts Association of Insurance Agents:

Question of the Week

Collision Coverage – If Hit by a Stolen Vehicle

Question: We had a prospect come into our office to insure his car. He said recently his car was hit while parked by a car that was stolen and involved in a police chase. He has collision, but when he made his claim through GEICO (former carrier), he was told it was not covered as it was a stolen car and a police chase. Now, I know that GEICO would probably have no one to subrogate against, but I believe as long as he paid a premium to have collision coverage, it should be covered less the deductible. I’ve been an agent for many years, but am I missing a caveat that denies coverage in this circumstance? If so, it’s a new one. Thanks.

Answer

Kathy Cormier: If your customer has first-party coverage (collision), they should be able to collect from their policy. I looked at GEICO’s policy, and they have a modified version of the MAP 2008:  https://massagent.com/wp-content/uploads/2023/01/gecc129849942.pdf. There was nothing that I saw saying they couldn’t collect under collision if damaged by a stolen vehicle. I’m including Irene Morrill, VP of Technical Affairs.

Irene Morrill: And that’s why people shouldn’t be insured with GEICO…they have no one to fight for them. I didn’t see any exclusion for “hit by a stolen vehicle” in the GEICO policy.

The person whose car was stolen is not legally responsible for the actions of the stolen vehicle – if the thief was caught…then the thief would be legally responsible for the damages, but if one buys Part 7 -it doesn’t matter.

I’d tell the client to make an insurance complaint…and say to the company that they are doing so…with the MA DOI – perhaps that will make the company decide to pay.

Filing an Insurance Complaint in Massachusetts


*This document is not a legal opinion and should not be relied upon as such. This document intends to provide a general background regarding the topic or topics discussed, not to provide legal advice. Producers and agencies should consult an attorney regarding specific situations and questions concerning the topic or topics covered in this document. Neither the Massachusetts Association of Insurance Agents, Number One Insurance Agency, nor any of its employees shall be responsible for any errors or omissions regarding any statements made in this document, nor any errors or omissions regarding any statutes, regulations, court rules, and/or any other government documents cited in this document.

Part 5, Optional Bodily Injury to Others

Optional Bodily Injury to Others


Coverage Review:  Part 5, Optional Bodily Injury to Others

As an insurance agent, when reviewing someone’s auto coverage, I immediately look at the Part 5, Optional Bodily Injury to Others, coverage. In my opinion, it’s the most important coverage on your policy. It’s your lawsuit coverage if you injure someone in an at-fault accident.

In addition to coverage, insurance companies provide legal defense.

We recommend limits of $250,000 per person/$500,000 per accident and a (minimum) $1,000,000 personal liability umbrella coverage.

Do you know how much coverage you have?

Give us a call or a click and let’s review.

President’s Day

MONDAY, FEBRUARY 17

“To encourage literature and the arts is a duty which every good citizen owes to his country.”―George Washington

In honor of President’s Day (& George Washington), following please find a list of some of Massachusetts’ world-class museums: 


What To Do if in an Auto Accident?

  • Stop. Be Courteous. Stay Calm. Your interest will be served best if you are courteous and engage in no controversy at the scene of the accident.
  • If there is significant damage to any of the vehicles or any potential injuries call 911 immediately.
  • Get the names of the owners and drivers involved. Get license numbers, telephone numbers, and registration numbers.
  • Get the names, addresses, and telephone numbers of witnesses.
  • Express no opinion as to who was at fault. Give no information except for as required by the authorities. Do not sign any statements unless required by authorities.
  • Report the claim promptly to Johnson & Rohan Insurance.

If off hours, following please find some of our companies’ off-hours claim reporting telephone numbers:

Travelers: 1-800-252-4633
Safety Insurance: 800-951-2100
Vermont Mutual: 1-800-435-0397

Plymouth Rock: 1-844-346-1225

Mass Property: 1-800-392-6108
Progressive Insurance: 1-800-274-4499
Bristol-West: 1-800-272-7865

Swyfft Insurance: 1-877-799-3389
Hagerty Insurance: 1-877-922-9701
Utica First Insurance: 1-800-456-2139

MAPFRE/Commerce: 1-866-351-2548
Grundy Insurance: 866-338-4006

Openly Insurance: 888-808-4842

Embark General: 800-809-5747

Happy Thanksgiving

Happy Thanksgiving from your friends at Johnson & Rohan Insurance

Happy Thanksgiving from your friends at Johnson & Rohan Insurance.

Johnson & Rohan Insurance is thankful for having you as a client.

We understand there are many places to buy your insurance. Our goal, as your independent agency, is to provide added value to our clients.

We constantly ask ourselves: “where do we add value?”

Value is saving you money and maximizing different companies’ discount programs.

Value is at claim time when you understand the coverage you’ve spent all this money on over the years.

Value is when you call our office and get a friendly & responsive voice.

Value is having an independent, insurance professional reviewing your coverage, shopping your insurance, and offering your trusted advice at claim time.

At Johnson & Rohan Insurance: we appreciate your business.

Thank you for insuring with us.

Happy Thanksgiving!

8 Homeowner Renewal Tips


  1. Study the renewal offer made by your insurance company. Does it look accurate?   Review the address, the Dwelling Value (this is the cost the insurance company thinks it would take to re-build your home if there was a catastrophic loss- it doesn’t include, land, driveway or basement).  Maybe better yet, ask us to review it for you!  Call and schedule a personal insurance review.
  2. Is there adequate coverage for Personal Property, also known as your “stuff”- clothes, furniture, electronics, art… in the past year have you purchased valuable jewelry, artwork or musical instruments? If so they can either be scheduled on your home policy or written on a standalone jewelry policy (usually a less expensive option too).
  3. Your Personal Property, is it insured with Replacement Cost Value or Actual Cash Value? It’s important if you ever have a loss- replacement cost would cover a new, like kind and quality rug, desk or couch while actual cast value would only cover the depreciated value.  There can be a huge difference in these values.
  4. Have you made any interior or exterior updates to your home? Added a pool, shed or cabana or expanded with a three-season porch?  If yes, you should discuss with us to make sure you have them covered.
  5. Have you added any smart home devices in the past year? Security systems for water, fire and theft can create discounts for your policy.
  6. Did you get a new pet in the past year? Most dog breeds are not a challenge for a homeowner policy, but some are.  Dog bites represent the single largest cause of homeowner liability claims- and different insurance companies have different lists of ineligible breeds.
  7. Most policies include an inflation adjustment automatically. It’s used to try to keep your home’s value current, taking inflation into account.  Sometimes though these automatic increases can outstrip actual inflation and homes become over-insured.  Look at the percentage your company uses, they can vary from 0% to 12%, or call us to discuss.
  8. Most homeowners use a typical deductible of $1000.  But depending on your circumstances, you may want to look at higher deductible options. $2500, $5000, $10,000 or $25,000 options with their lower annual premiums are more common than your may realize.